










Submission received
Your information has been recorded by WONE.
Sourced guides to doing business in each market, and the status of every service there. Partners are in place in 29 markets so far.
One WONE Global Partner for each service in each market. Start from what you need to do, or go straight to a service.
Licences, value chains and the questions businesses in each industry ask first, with the services that usually apply.
Ask WONE Global what applies to your industry in a market, with the sources shown.
What one country changes for the other, worked journeys step by step, and who handles each side.
Named senior professionals, each admitted as the one firm for a service in their country, and the firms they lead.
One Partner per service, per country, admitted by review against published criteria.
Every statement is dated and sourced, and says whether it has been checked or professionally reviewed.
Answers come from statements checked against official sources, with the sources shown. Research, not advice.
Legal, tax, audit, accounting and advisory work across 100 countries, with one contact and one published Standard.
Africa · WONE Global market
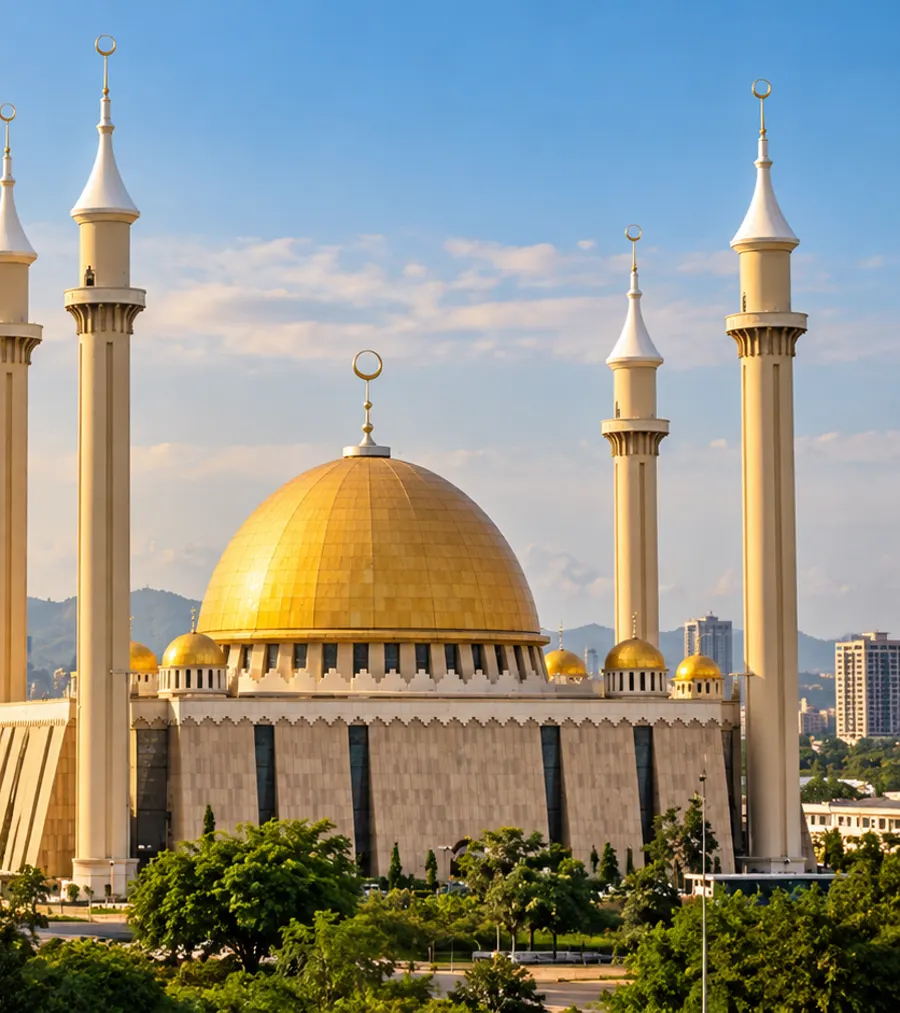
Nigeria is covered by WONE for cross-border business discovery, with links to relevant expertise, professionals, industries and market intelligence. No WONE Global Partner is in place here yet. WONE Global confirms on request whether a vetted Associate firm can act, before anything begins.
Lagos · Tuesday 20 October
--:--
Local time
Market guide · Source-checked research
Nigeria is a federal republic where company law, investment promotion and most business taxes are federal, while personal income tax on residents is administered by the states. A comprehensive tax reform package (the Nigeria Tax Act and Nigeria Tax Administration Act 2025) commenced in January 2026 according to the gazetted text, keeping companies income tax at 30 percent, exempting small companies and introducing a 4 percent development levy. Foreign investors may own up to 100 percent of most businesses, and profits are guaranteed transferable through authorised dealers. Data protection is governed by the Nigeria Data Protection Act 2023.
Essentials guide · Source-checked research100% of statements checked against a source38 checked against an official source0 checked against a secondary sourceChecked 2026-10-19Not yet professionally reviewed
Nigerian law is based on English common law, supplemented by federal and state statutes. Companies are incorporated with the Corporate Affairs Commission under the Companies and Allied Matters Act 2020, and foreign-owned businesses also deal with the Nigerian Investment Promotion Commission. The Nigeria Revenue Service (formerly the Federal Inland Revenue Service) administers company taxes and VAT, the Central Bank of Nigeria regulates banking and foreign exchange, the Federal Competition and Consumer Protection Commission reviews mergers, and the Nigeria Data Protection Commission enforces data protection.
Key facts
Foreign investors usually incorporate a private company with CAC; one person can form one, and most sectors allow full foreign ownership. Companies with foreign shareholders face a higher minimum share capital, must disclose persons with significant control and must obtain a Tax ID.
Key facts
A single person can form a private company; the general minimum share capital is N100,000.
CAC's checklist sets N10 million minimum share capital where there is foreign participation; confirm the current figure.
Foreign ownership up to 100 percent is permitted outside the NIPC Act negative list, subject to sector rules.
Anyone with 5 percent or more of shares or votes, or other significant control, must be disclosed to CAC.
Register for a Tax ID early: it is needed for compliance and for any government contract.
Who handles this in NigeriaSetting up and running a companyLicences, permits and regulators
Questions on this topic
6 statements on entry, investment and company formation in Nigeria
The 2025 tax laws keep companies income tax at 30 percent, exempt small companies and add a 4 percent development levy and a 15 percent minimum effective rate for large groups. VAT stays at 7.5 percent. Returns are due six months after year end, and related-party dealings must be at arm's length.
Key facts
Companies income tax is 30 percent; small companies with turnover up to N100 million and assets up to N250 million pay 0 percent.
Add the 4 percent development levy when modelling the effective rate for non-small resident companies.
Large multinational and domestic groups face a 15 percent minimum effective tax rate.
VAT is 7.5 percent with zero rating for non-oil exports and certain essentials.
File the annual return within six months of year end, and price related-party transactions at arm's length.
Who handles this in NigeriaTax and structuringAccounting and annual filings
Questions on this topic
6 statements on tax, accounting and reporting in Nigeria
Foreign staff need an expatriate quota position, except in export processing zones. Employee income tax is administered by the state of residence. Minimum wage, pension and labour law rules were not confirmed for this guide.
Key facts
Plan expatriate quota positions before hiring foreign staff.
NEPZA zone enterprises are exempt from expatriate quotas.
Payroll tax for resident employees is administered by state tax authorities, not the NRS.
Who handles this in NigeriaEmployment, payroll and immigration
Questions on this topic
3 statements on employment, payroll and mobility in Nigeria
The new Economic Development Tax Incentive replaces Pioneer Status for priority sectors, and free zones offer broad tax exemptions. Sector licensing was not sourced.
Key facts
The Economic Development Tax Incentive gives a 5 percent annual credit on qualifying capital spending for five years in priority sectors.
NEPZA zone enterprises are exempt from all tiers of tax on zone income and may be fully foreign owned.
Oil and gas free zones offer a tax holiday and a 75 percent duty rebate on processed raw materials.
Who handles this in NigeriaLicences, permits and regulatorsTax and structuring
Questions on this topic
3 statements on licensing, incentives and sector rules in Nigeria
Foreign investors are guaranteed transferability of dividends, loan payments and sale proceeds through authorised dealers, which in practice depends on documenting inflows under Central Bank rules. CBN foreign exchange and account-opening rules were not confirmed.
Key facts
The NIPC Act guarantees transfer abroad of dividends, loan servicing and sale proceeds through authorised dealers.
Document capital inflows in line with CBN rules, such as Certificates of Capital Importation.
Free repatriation of capital and profits is also guaranteed in NEPZA zones.
Who handles this in NigeriaPayments and currencyBanking and capital
Questions on this topic
3 statements on banking, exchange control and repatriation in Nigeria
Nigeria applies the ECOWAS Common External Tariff and duty-free trade within ECOWAS for qualifying goods, with targeted import duty exemptions and free zone relief.
Key facts
Tariffs follow the ECOWAS Common External Tariff.
Goods originating in ECOWAS states can move duty free under the Trade Liberalisation Scheme.
Power, agricultural and mining machinery can qualify for 0 percent import duty.
Free zone enterprises need no import or export licences but face limits on sales into the domestic market.
Who handles this in NigeriaCustoms, trade and export controls
Questions on this topic
4 statements on customs, trade and supply chain in Nigeria
The Nigeria Data Protection Act 2023 is enforced by the Nigeria Data Protection Commission. Transfers abroad need adequate protection or an approved transfer instrument, annual audit returns are due by 31 March, and the tax authority is introducing an electronic fiscal system.
Key facts
The NDPA 2023 and the NDPC set the framework for processing personal data.
Cross-border transfers need adequacy, an approved transfer instrument or another lawful basis.
Major-importance controllers face fees of up to N10 million or 2 percent of revenue, whichever is greater.
File compliance audit returns through a licensed compliance organisation before 31 March.
Expect to connect invoicing systems to the NRS Electronic Fiscal System once it is deployed.
Who handles this in NigeriaData protection and cyber
Questions on this topic
5 statements on data protection and cyber in Nigeria
Nigeria is a PCT state. National trade mark, patent and copyright rules could not yet be checked for this guide.
Key facts
International patent applications can enter Nigeria through the PCT.
Who handles this in NigeriaTrade marks, patents and brands
Questions on this topic
1 statement on intellectual property in Nigeria
Notifiable mergers must be approved by the FCCPC before implementation, and offshore deals can be caught where the parties sell into Nigeria. Corporate capital gains are taxed at 30 percent.
Key facts
Do not implement a notifiable merger before FCCPC approval.
Notification depends on Nigerian turnover thresholds; confirm the current figures before signing.
Foreign-to-foreign deals can be notifiable where the parties sell into Nigeria.
Phase One review runs 20 business days for small mergers and up to 60 for large ones.
Corporate capital gains on disposals are taxed at 30 percent.
Who handles this in NigeriaBuying, selling and investingTax and structuring
Questions on this topic
5 statements on m&a, competition and restructuring in Nigeria
Only the NIPC Act guarantee against expropriation could be confirmed. Anti-bribery, AML and sanctions rules need to be checked from official sources.
Key facts
Investments are protected against nationalisation and expropriation without fair and adequate compensation.
Who handles this in NigeriaAnti-bribery, sanctions and compliance
Questions on this topic
1 statement on anti-corruption, aml and compliance in Nigeria
Nigeria is a New York Convention state with reciprocity and commercial reservations. The domestic arbitration statute and court enforcement of foreign judgments were not confirmed.
Key facts
Foreign awards from other contracting states arising from commercial relationships are enforceable under the New York Convention.
Who handles this in NigeriaDisputes and arbitration
Questions on this topic
1 statement on disputes and enforcement in Nigeria
Sources last checked on 19 October 2026. None of it has been professionally reviewed yet: it is research checked against official and secondary sources by WONE Global, not legal or tax advice.
WONE Global Intelligence
Choose a question or ask your own. Answers draw on WONE Global's market guides, and are set out in clear sections: the answer, the rules, the figures, what it means for you, the risks and who can help.
No question in the library matches. Ask it in your own words.
How answers are set out
Research, not legal or tax advice. Before acting, confirm with a qualified professional in each country involved. Sign in to save an answer.
Who handles your work
Tell us what you need. WONE Global confirms whether a vetted Associate firm can act, tells you who it is and checks for conflicts before any work starts. You agree scope and fees with that firm directly.
On request
No WONE Global Partner holds this yet. Send us your requirement: WONE Global confirms whether a vetted Associate firm can act, tells you who it is and checks for conflicts before any work begins.
Send your requirement →Save your questions, decisions and WONE activity in one account.
Forgot your password? Reset it securely.
Partner workspaces are for Partner firms. Explore partnership →